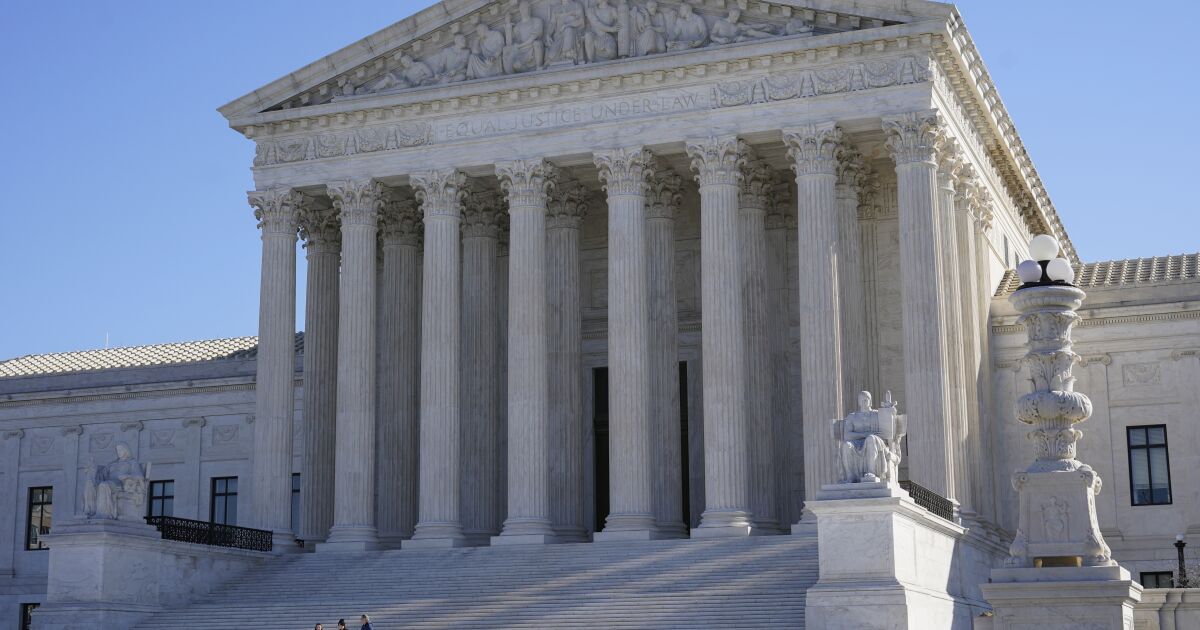
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.
The Supreme Court announced Monday it will weigh in on the constitutionality of wealth taxes by deciding whether Congress may require taxpayers to pay their share of earnings from a foreign company, even if they received no dividends or income.
The case of Charles and Kathleen Moore, and their $14,729 tax bill, has garnered much attention on the right because of what it could mean if progressive Democrats take control of Congress.
The 16th Amendment says Congress has the power to “lay and collect taxes on incomes, from whatever source derived.” And that has been understood to mean that the government may impose taxes on wages or earnings and stock dividends, but not on property or corporate wealth that grows in value. These are referred to as “unrealized gains.”
But last year, the 9th Circuit Court upheld part of the 2017 tax bill passed by the Republican-controlled Congress which imposed a one-time tax on Americans who owned shares in foreign corporations that gained in value.
The Moores said they received no income or dividends from their investment in a company in India which supplies equipment to small farmers, and they sued, alleging the tax was unconstitutional. They lost before a federal judge and appeals court.
“There is no blanket constitutional ban on Congress disregarding the corporate form to facilitate taxation of shareholders’ income,” the appeals court said. “In other words, there is no constitutional prohibition against Congress attributing a corporation’s income pro-rata to its shareholder.”
But lawyers for the Moores, backed by the U.S. Chamber of Commerce and other business groups, urged the high court to hear the appeal.
They said the 9th Circuit’s opinion “gutted the Constitution’s key limit on the federal taxing power” by sweeping away the essential restraint on Congress’ taxing power and opening the door to unapportioned taxes on property and anything else Congress might deem to be income.
“The Constitution does not allow Congress to point at any pot of money and call it ‘income’ and then income-tax it,” said Andrew M. Grossman, the Moores’ lead counsel. “‘Income’ means the same thing now that it did when the 16th Amendment was ratified: gains that have been realized by the taxpayer.”
The high court will hear the case of Moore vs. United States in the fall.