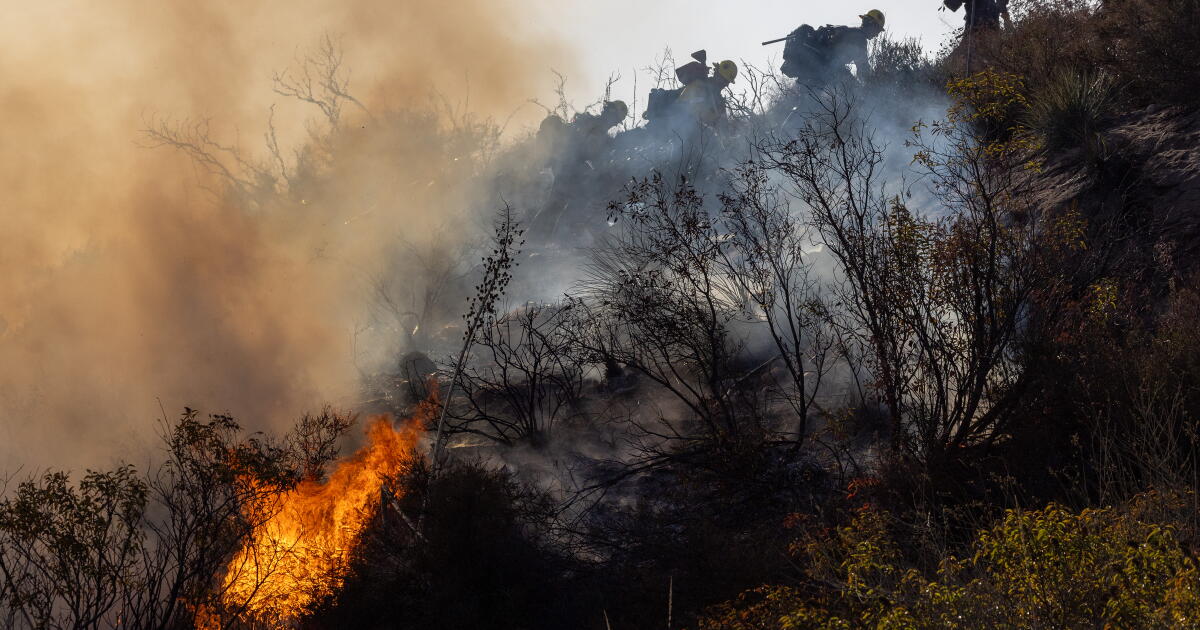
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.
A revolution is underway in California’s insurance market that could provide relief to homeowners in high-fire-risk neighborhoods who have found it difficult to find insurers to cover their homes, typically a household’s most valuable asset.
Under the new rules, state insurers for the first time will be allowed to use so-called catastrophe models to help determine the cost of home insurance. The models, developed by firms such as Verisk Analytics and Moody’s, are complex computer programs that aim to better determine the risk a structure faces from wildfires amid a changing climate. Here are five things to know about the models:
How do these models work?
The programs, first developed in the 1980s because of hurricane losses and increasingly applied to wildfires, typically run thousands of possible scenarios that allow insurers to determine their potential financial exposure in a disaster. The models are proprietary but take into account many factors, including meteorological conditions, an area’s topography, the amount of brush and other nearby fuel, and a community’s building density.
When setting individual home premiums, California is requiring insurers to consider a building owner’s fire mitigation efforts, such as installing a Class A fire-rated roof, closing eaves or doing brush removal.
Will the models increase the availability of insurance?
The regulations are intended to sharply increase the availability of insurance in areas that have high fire risk as defined by Department of Insurance maps released this year, which are expected to be updated soon. Homeowners in those areas have been flocking to the FAIR Plan, the state’s insurer of last resort, which sells bare-bones policies. Southern California neighborhoods in those maps include ZIP Codes in Malibu, Beverly Hills and other communities in mountainous areas.
In exchange, large insurers are supposed to write policies in those neighborhoods equivalent to 85% of their statewide market share, meaning an insurer with a 10% statewide share should cover 8.5% of homes. However, critics such as Consumer Watchdog in Los Angeles say that those regulations have loopholes and that insurers have leeway to not meet that benchmark.
How will the new regulations affect my property insurance rates?
That’s a matter of debate. Catastrophe models are not specifically intended to lower rates, but insurers and the insurance department maintain that catastrophe models, by allowing insurers to more accurately calculate their risk, should allow for more gradual rate increases over time rather than requests for large one-time rate hikes, such as the 30% increase sought by State Farm last summer.
Consumer Watchdog, however, says the models will lead to sharp rate hikes because the regulations allow insurers to keep essential details about the models under wraps despite a public review process established by the insurance department. The department disagrees and is supporting the establishment of a “public” model being developed by Cal Poly Humboldt and others that could be used in the future as a benchmark to evaluate the private models.
Will the new regulations affect me if I live in a city and not a wildfire zone?
Yes, sort of. Insurers in the state already include the risk of wildfire in their premiums, but it is based on historical claims data. Homes in neighborhoods that don’t face such a risk already pay lower rates, and that is not expected to change under the new rules. However, even homeowners in low-risk urban areas are facing rate hikes, and the department is hoping that the regulation along with other regulatory changes — such as allowing insurers to include the cost of reinsurance in their premiums — will draw more insurers back into the market. Reinsurance is acquired by insurers from other insurers to help protect them from catastrophic losses.
When can I start seeing some relief?
The insurance department will start accepting applications from modeling companies on Jan. 2 and expects that, after the public review process is completed, some could be approved in the first quarter. Insurers could then file for new rates based on those models. Those rate filings also must undergo a review that the department said could be completed for some as early as next summer, with more in 2026.